Citibank Credit Card Guide: Cards, Fees, Eligibility and How to Apply in the UAE
Choosing a credit card in the UAE usually starts with a simple question: which card gives me the most for the way I actually spend? A Citibank credit card is often on the shortlist because Citi has been banking in the country since 1964, and its card range is built around cashback, travel and everyday lifestyle perks rather than around mass-market retail banking.
This guide explains how the Citi range is laid out, who each card suits, what it really costs after the first year, and how to apply without wasting a credit enquiry on a card you will not qualify for.
Quick answer: A Citibank credit card is a card issued by Citibank N.A. – UAE Branch to residents aged 21 or above with an Emirates ID and a minimum monthly salary from AED 5,000. The range runs from the free Citi Simplicity to the premium Citi Ultima, covering cashback, rewards, travel and lifestyle benefits.
What Makes Citibank Credit Cards Different in the UAE?
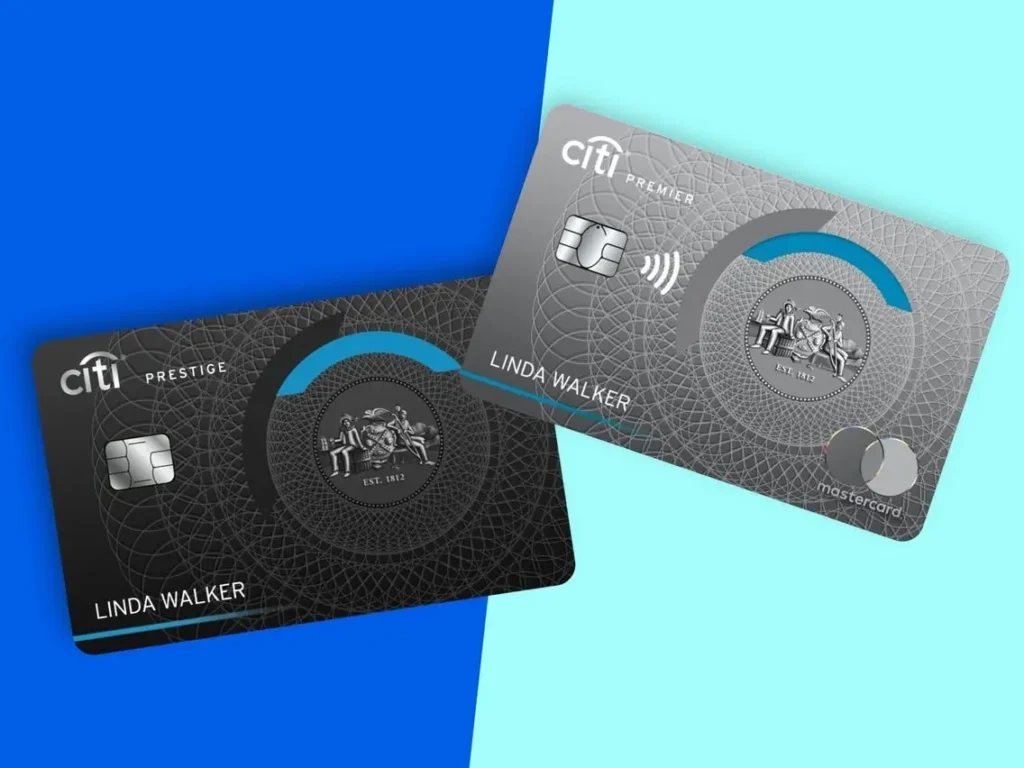
Most UAE banks sell cards as a side product of a current account. Citi positions itself closer to a wealth and cards specialist. Its UAE footprint is small, with a handful of branches and Citigold lounges in Dubai and Abu Dhabi, but its card line-up is deliberately tiered. You move up the ladder as your salary, spending and travel habits grow.
That tiering is the first thing to understand. Citi does not ask you to pick from dozens of near-identical cards. It gives you seven, and each one has a clear job.
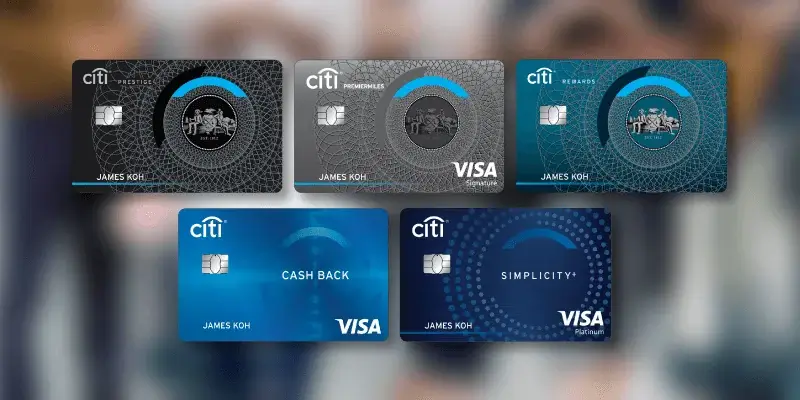
The Citibank Credit Card Range at a Glance
| Card | Built for | Typical annual fee* | Approx. minimum salary |
|---|---|---|---|
| Citi Simplicity | First-time cardholders who want no penalty fees | AED 0 | AED 5,000 |
| Citi Cashback | Everyday and international spending | AED 0 in year one, then spend-based | AED 8,000 |
| Citi Rewards | Points earners, grocery and overseas spend | AED 0 in year one, then spend-based | AED 8,000 |
| Citi Ready | Instalment-style spending and a higher limit | Waived on current offer (normally AED 300) | AED 8,000 |
| Citi Premier | Rewards plus light travel perks | AED 750 | About AED 15,000 |
| Citi Prestige | Frequent travellers | AED 1,500 | About AED 25,000–30,000 |
| Citi Ultima | Premium travel and lifestyle | AED 3,000 | AED 36,750 |
*Fees are before 5% VAT. Salary thresholds differ slightly between Citi’s own pages and third-party listings, so confirm the figure for your card on Citi’s website before you apply.
Entry-Level Cards: Simplicity, Cashback, Rewards and Ready
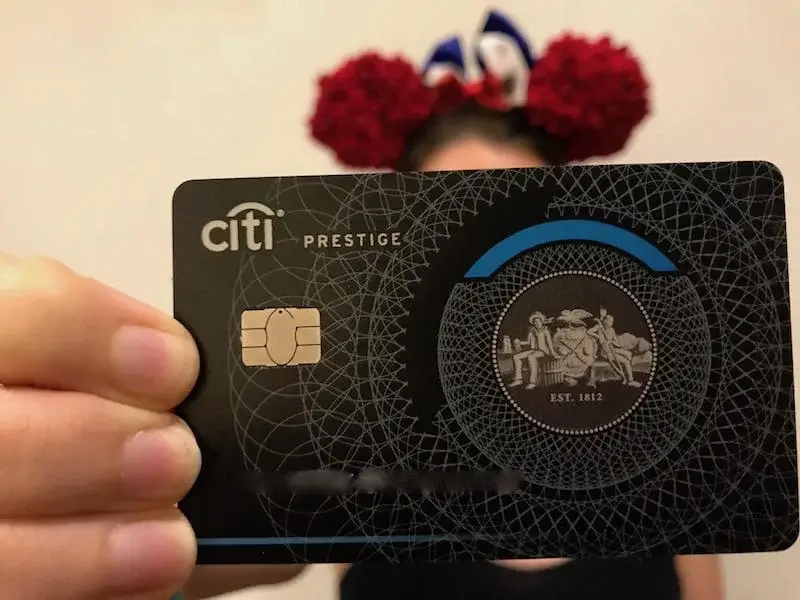
Citi Simplicity
Simplicity is the card for people who fear fees more than they want rewards. Citi markets it with no annual fee and no late fee, cash advance fee or over-limit fee. With the lowest salary requirement in the range, it is a sensible first card, and paying on time builds the credit history that unlocks better cards later.
The trade-off is obvious. You will not earn much in return, so treat it as a starter card, not a long-term rewards machine.
Citi Cashback
Citi Cashback pays 3% on spending in foreign currency, 2% on groceries and 1% on everything else. There is no monthly cap up to your credit limit, no minimum spend to trigger the rate, and no redemption step; the cashback arrives automatically.
That structure suits two kinds of people. The first is anyone who shops on international websites or travels often, because a 3% return on non-dirham spend broadly covers the foreign-currency fee. The second is a household that spends heavily at supermarkets.
The catch sits in the fine print. The card carries no annual fee in the first year. From year two, the fee is waived only if you spend at least AED 9,000 during the year; otherwise AED 300 applies. Most active users clear that bar easily, but a card that sits in a drawer will not.
Citi Rewards
Citi Rewards swaps cashback for ThankYou points. Grocery and non-AED purchases earn 1.5 points per dollar, while local spending earns 1 point. Points are useful if you prefer vouchers and flexible redemptions over a flat percentage back.
The same year-one and AED 9,000 spend rules apply as with Citi Cashback. If you cannot decide between the two, run a simple test: add up a typical month of groceries and international spending. When that total is large, cashback usually wins on simplicity. When you enjoy collecting points for specific rewards, Rewards is the better fit.
Citi Ready
Citi Ready targets people who like to split larger purchases into instalments and want a generous limit. Citi’s pages describe the annual fee as waived indefinitely under the current offer, with the normal fee being AED 300. Because offers like this can change, check the fee status on the day you apply.
Premium Cards: Premier, Prestige and Ultima
Citi Premier
Premier is the first rung where travel perks appear alongside rewards. It carries an AED 750 annual fee, and recent welcome offers have come as a statement credit once you pay the fee and meet a minimum spend. It makes sense if you spend enough on the card to earn back the fee in points, and if you use the lounge and lifestyle perks at least a few times a year.
Citi Prestige
Prestige moves the card firmly into travel territory, with an AED 1,500 annual fee and a higher salary bar. Third-party listings describe Priority Pass airport lounge access for the cardholder, with guest entitlements depending on the current programme terms. If you fly several times a year, the lounge visits alone can justify the fee. If you fly twice a year, they probably cannot.
Citi Ultima
Ultima sits at the top. Citi launched it in the UAE together with Mastercard for affluent clients, and it carries a AED 3,000 annual fee with a minimum salary of AED 36,750. It is a high-spend travel card, and the value only stacks up if you actually use the airline, hotel and concierge-style benefits.
A good rule across all three premium cards: calculate the benefits you will really use in twelve months, subtract the fee plus VAT, and see whether anything is left. If the answer is no, step down a tier.
Citibank Credit Card Eligibility Requirements
Eligibility is simple on paper, though approval is always at the bank’s discretion.
- Age: 21 or older.
- Residency: UAE resident with a valid Emirates ID and residence visa.
- Income: Salary requirement depends on the card, starting at AED 5,000 per month.
- Employment: Salaried staff are the main target; some self-employed professionals can qualify.
- Credit history: Citi checks your Al Etihad Credit Bureau (AECB) record, so a clean repayment history helps.
Before you apply, it is worth knowing where you stand. Our guide on how to check your credit score in the UAE walks through the AECB report and what the score bands mean.
Documents You Will Typically Need
Expect to provide your Emirates ID, passport and residence visa copy, a salary certificate or recent payslips, and recent bank statements. Citi may ask for extra documents depending on your employer and income type.
Fees, Interest and Charges You Should Understand
Annual fees are only part of the cost. These are the items that most often surprise new cardholders.
VAT on the annual fee. Citi applies 5% VAT on top of the stated annual fee.
Cash advances. Most Citi cards charge about 3% of the amount withdrawn, with a minimum of AED 99 per transaction, and interest starts immediately. Simplicity is the exception, as Citi advertises it with no cash advance fee.
Foreign-currency spending. International transactions usually carry a foreign-currency markup. Citi Cashback’s 3% return on non-AED spend is designed to offset it.
Interest on unpaid balances. Third-party comparison sites list monthly rates around 3.5%, which is typical for the UAE market. Treat a credit card as a payment tool you clear in full each month, not as a loan.
Because the UAE Central Bank sets consumer protection rules for cards and interest, it is also worth reading the regulator’s guidance before you carry a balance.
How to Apply for a Citibank Credit Card
- Pick the card that matches your salary. Applying for a card above your income tier is the fastest way to a rejection that shows on your credit report.
- Check your AECB score. Fix errors first; do not apply on impulse.
- Apply through Citi’s official channels. Citi’s welcome offers have often been limited to customers who apply directly on its website, so applying through a third party can mean losing the bonus.
- Upload your documents. Keep your Emirates ID, visa and salary proof ready.
- Wait for the decision. Citi may call you to verify employment or details.
- Activate and set up autopay. Pay at least the minimum automatically, and the full balance whenever possible.
Welcome Offers: Read the Conditions Before You Chase Them
Citi regularly runs statement-credit offers tied to minimum spend within 60 or 90 days, and on premium cards the credit is often paid after you settle the annual fee. Offer values and spend targets change several times a year. A bonus is only worth having if you would have spent that amount anyway, so never inflate your spending to hit a target.
Common Mistakes to Avoid
- Applying for several cards in a short window, which can lower your credit score.
- Ignoring the spend condition that keeps the annual fee waived from year two.
- Using cash advances for everyday needs.
- Choosing a premium card for the status rather than the benefits you will use.
- Missing the payment due date because autopay was never set up.
Citibank vs. Other UAE Card Issuers: How to Decide
Compared with the big local banks, Citi’s strengths are clean cashback mechanics on its entry cards and a clear premium ladder. Its weaker side is physical reach: there are no Citi retail branches outside Dubai and Abu Dhabi, so if you want in-person service in the other emirates, check how comfortable you are with digital banking first.
If you are comparing across issuers, our related guides on the FAB Gold Credit Card, the FAB Elite Credit Card and the American Express Credit Card cover other options side by side.
Managing Your Citi Card Day to Day
Citi runs its servicing through the Citi Mobile app and online banking, where you can check statements, track application status and manage payments. Citi also offers PayAll, a payment service that lets cardholders pay large bills, such as rent or school fees, with the card and earn rewards. Fees may apply to such payments, so compare the cost with the rewards before you use it.
Future Outlook: What to Watch
The UAE card market keeps moving toward instant digital approvals, lifestyle partnerships and tighter lending rules. Citi has also been reshaping its global consumer business for several years, so it is wise to confirm that the card you want is open to new applicants and to check any announcements from Citi or the Central Bank before you apply.
FAQs
1. What is the minimum salary for a Citibank credit card in the UAE?
It starts at AED 5,000 per month for Citi Simplicity. Citi Cashback, Rewards and Ready generally need AED 8,000, while premium cards need considerably more, up to AED 36,750 for Citi Ultima.
2. Which Citibank credit card is best for cashback?
Citi Cashback is the dedicated cashback card, paying 3% on non-AED spend, 2% on groceries and 1% on other purchases with no monthly cap.
3. Does Citibank charge an annual fee?
Yes, but it varies. Simplicity has none, entry cards are free in year one with a spend-based waiver afterwards, and Premier, Prestige and Ultima carry AED 750, AED 1,500 and AED 3,000 respectively, plus 5% VAT.
4. How do I keep the annual fee waived on Citi Cashback or Citi Rewards?
Spend at least AED 9,000 in the year. If you fall short, an AED 300 fee applies.
5. Is the Citi Simplicity card really free?
Citi advertises it with no annual fee and no late fee, cash advance fee or over-limit fee. Interest still applies if you carry a balance.
6. Which Citi card is best for travel?
Prestige and Ultima are the travel-focused cards. Premier offers a lighter version. Compare the benefits you will use with the fee before choosing.
7. Can I get a Citibank credit card as an expat?
Yes. You need a valid Emirates ID and UAE residence visa, and you must meet the salary requirement for the card.
8. Do I need a good credit score to qualify?
Citi checks your AECB record, so a clean repayment history improves your chances. Late payments and high existing debt can lead to a rejection.
9. How long does approval take?
Timelines vary by card and how complete your documents are. Citi may contact you to verify details, which can add time.
10. How do I check my Citi credit card application status?
Use the Citi Mobile app or online banking, or call Citi customer service.
11. Can I withdraw cash with a Citibank credit card?
You can, but cash advances usually cost about 3% with a AED 99 minimum, and interest begins right away. Simplicity is advertised without a cash advance fee.
12. Are Citibank credit cards still open for new applications?
Citi’s UAE website has been accepting applications, but a third-party listing has claimed that the UAE consumer business is moving to another bank. Confirm the current status directly with Citi before you apply.
Conclusion
A Citibank credit card works best when you match the card to your salary and spending habits. Citi Simplicity gives beginners a low-risk start, Citi Cashback and Citi Rewards suit everyday and international spenders, and Premier, Prestige and Ultima reward people who genuinely use travel and lifestyle benefits.
Before you apply, check your credit score, calculate the real annual cost after VAT and the spend-based fee waiver, and confirm current offers on Citi’s own website. A card is only a good deal when its benefits outweigh what it costs you.
Sara is a UAE-based banking and accounting expert with over 4 years of professional experience in the financial sector. Her expertise spans retail banking, financial reporting, compliance, and practical money management topics relevant to individuals and businesses in the UAE.
She contributes clear, accurate, and well-researched financial content, simplifying complex banking and accounting concepts for everyday readers. Sara’s writing reflects strong industry knowledge, regulatory awareness, and a commitment to financial accuracy and transparency.