NBQ Credit Card Guide: Gold, Platinum and Infinite Cards Compared (2026)
By the Emirates Breaking Editorial Team | Updated October 2026
Quick answer: The NBQ credit card lineup from National Bank of Umm Al Qaiwain includes three Visa cards: Gold (free, salary from AED 8,000), Platinum (AED 500 annual fee, salary from AED 15,000) and the invitation-only Infinite (AED 1,000, salary from AED 30,000). All offer up to 55 interest-free days, with a 29.88% APR on unpaid balances.
Most people in the UAE can name the big Dubai and Abu Dhabi banks without thinking. Far fewer know that a bank founded in the emirate of Umm Al Quwain has quietly built one of the more straightforward card ranges in the country. The NBQ credit card family is small, easy to understand and priced openly, which is rare in a market where fee schedules can run to several pages.
This guide explains what each NBQ card offers, who qualifies, what every fee actually costs you, and where the real trade-offs sit. Whether you are a salaried resident, a UAE national or a business owner who wants a card in your own name, you will find the numbers you need to decide.
What Is the NBQ Credit Card?
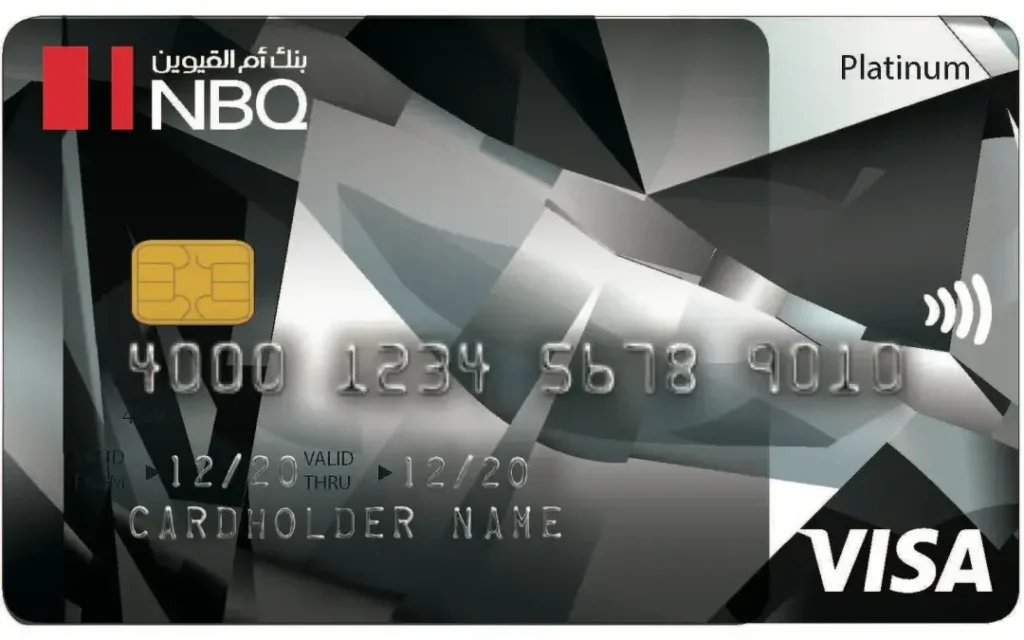
NBQ is the short name of the National Bank of Umm Al Qaiwain (PSC), a UAE bank created by an Amiri Decree in January 1982 and listed on the Abu Dhabi Securities Exchange under the ticker NBQ. The Umm Al Quwain government is its largest shareholder. The bank serves retail, SME and corporate clients through 17 branches and 13 electronic banking units across the country, and it runs an Islamic banking window that has operated since 2005.
An NBQ credit card is a Visa-network card issued by that bank. The range has three tiers, named Gold, Platinum and Infinite, and the tier you receive depends mainly on your monthly income. Each card is a revolving credit line. You spend up to your limit, receive a statement, and either pay in full to avoid interest or carry a balance and pay finance charges.
Two features set NBQ apart from many competitors. First, the bank publishes a Key Facts Statement, a short regulatory document that lists fees, interest, eligibility and a worked example of how interest is calculated. Second, salary transfer is not mandatory for any of the three cards, which matters if your employer pays you into another bank.
NBQ Credit Cards at a Glance
The table below summarises the three tiers using NBQ’s own published figures.
| Feature | Gold | Platinum | Infinite |
|---|---|---|---|
| Monthly salary band | AED 8,000 to 14,999 | AED 15,000 to 29,999 | AED 30,000 and above |
| Annual fee | Free | AED 500 | AED 1,000 |
| Access | Open application | Open application | Invitation only |
| Interest-free period | Up to 55 days | Up to 55 days | Up to 55 days |
| Airport lounges | Not listed | Priority Pass | Priority Pass and LoungeKey |
| Travel insurance | Free worldwide | Free worldwide | Free worldwide |
| Supplementary card | 1 free | 1 free | 1 free |
| Card, PIN and duplicate statement fees | Charged | Charged | Waived |
NBQ Gold Credit Card
Gold is the entry point and, for many applicants, the best value in the range. It carries no annual fee, which means you can keep it for years without paying to hold it. The card is contactless, so you can tap to pay and skip the PIN on purchases up to AED 500.
It also includes free worldwide travel insurance when you buy your tickets with the card. The cover is broad: medical expenses, emergency evacuation and repatriation, trip cancellation, travel and baggage delay, lost baggage and money, document replacement, personal liability, hijack cover and legal expenses. For an occasional traveller, that insurance alone can offset the cost of a separate policy.
The main limit is the salary floor. The AED 8,000 minimum is higher than the entry point listed by several larger banks, so Gold suits people who are already comfortably established rather than those building a first credit history.
NBQ Platinum Credit Card
Platinum adds travel and lifestyle perks to everything Gold offers. The key upgrade is airport lounge access through Priority Pass, which NBQ’s key facts document describes as covering more than 1,200 lounges in 143 countries (the bank’s website rounds this up to 1,300). The Visa programme also brings a Dine and Fly airport dining option and purchase protection with extended warranty benefits.
NBQ also promotes 50% off at major golf courses for Platinum holders. The annual fee is AED 500. Whether that is worth paying comes down to travel frequency. If you fly four or five times a year and would otherwise pay for lounge entry, the fee can earn itself back quickly. If you rarely leave the country, Gold is the more rational choice.
NBQ Infinite Credit Card
The Infinite card is invitation only, so you cannot simply apply and wait for approval. NBQ selects holders, typically from clients with salaries of AED 30,000 or more. The annual fee is AED 1,000.
In return you receive Priority Pass and LoungeKey access, 24/7 concierge services, hotel booking discounts and a higher spending limit. NBQ’s published limits allow up to AED 200,000 per point-of-sale transaction and AED 100,000 per online transaction, compared with AED 100,000 and AED 20,000 on Gold. Infinite holders also avoid card replacement, PIN replacement and duplicate statement charges.
If you earn at this level and want to be considered, the practical route is to build a relationship with the bank first, for example through a salary or savings account, and ask your relationship manager about eligibility.
NBQ Credit Card Eligibility
Eligibility depends on your employment type, income and how long you have been in your role.
If you are a salaried employee
- You must be 21 or older and either a UAE national or a UAE resident.
- Your monthly salary must be at least AED 8,000.
- You need at least one year of service.
- Your employer should be a government body, a semi-government entity or a private company accepted by the bank.
- Salary transfer is not mandatory.
If you are self-employed
NBQ treats business owners and partners differently, and the rules are stricter. Your business should be at least three years old with annual turnover of at least AED 500,000. Your bank statement should show an average balance of at least twice the credit limit you want, with a minimum of AED 20,000. The offer applies to owners and partners who want a credit card as a standalone product.
Because the bank takes more security here, you should expect to provide an undated cheque for 120% of the card limit, drawn on the account whose statement supports your application. Final limits for self-employed customers are at the bank’s sole discretion.
If you want a card against a deposit
NBQ can also issue a card secured by a fixed deposit with 100% coverage, using a lien letter. This is a useful route when your salary does not meet the standard bands. Note that if you later close the card, you can only withdraw the deposit 45 days after the card is paid off and closed.
Documents You Need
The checklist is short. Prepare these before you apply:
- A valid Emirates ID and passport copy.
- Proof of income, such as a salary certificate, a salary transfer letter or recent bank statements.
- Any additional documents NBQ requests at its discretion.
Infinite applicants provide their Emirates ID and passport, and the bank may ask for more. Make sure every document is current. An expired Emirates ID is the most common reason for avoidable delays.
NBQ Credit Card Fees and Charges
Fees decide whether a card is cheap or expensive in real life. NBQ’s Key Facts Statement lists them clearly, and all amounts include VAT.
| Charge | Amount |
|---|---|
| Annual fee | Gold free, Platinum AED 500, Infinite AED 1,000 |
| Cash advance fee | 3.15% of the amount plus AED 21 |
| Late payment fee | AED 157.50 per month |
| Over-limit fee | AED 157.50 per billing cycle |
| Returned payment (cheque or direct debit) | AED 131.25 |
| Card replacement | AED 78.75 (free on Infinite) |
| PIN replacement | AED 52.50 (free on Infinite) |
| Duplicate statement | AED 47.25 per month (free on Infinite) |
| Liability or no-liability letter | AED 52.50 |
| Temporary limit increase | AED 52.50 |
| Invalid disputed transaction | AED 157.50 |
| International courier | AED 157.50 |
| Foreign currency transaction | 2.49% on spend outside the UAE |
How interest works
The annualised percentage rate (APR) is 29.88%, or 2.49% per month, and the same rate applies to cash advances. Pay your full statement balance by the due date and you pay no interest on purchases. Miss that target and interest runs on the whole outstanding balance from the transaction dates, not only on the unpaid portion.
The minimum payment is the sum of fees, interest, instalments, any over-limit and overdue amounts, plus 5% of the principal balance. To see what that means, imagine you carry AED 5,000 into the next month. Interest alone is roughly AED 125, and your minimum payment would be about AED 250 plus that interest and any fees. Pay only the minimum and the balance shrinks slowly while finance charges keep accruing. NBQ states this plainly in its own warning.
The 55-day interest-free window applies only to retail purchases. It does not apply to cash advances, balance transfers or special promotions, and cash advances start charging interest on the day you withdraw.
What spending abroad really costs
NBQ charges 2.49% on every foreign currency transaction, and Visa adds its own processing charge of roughly 1.15%. On AED 1,000 of overseas spending, that is about AED 36 in total. There is a second trap: if a merchant offers to charge you in dirhams at the point of sale, NBQ may also apply a 2.49% conversion fee on top of the merchant’s own exchange margin. Always choose to pay in the local currency.
Flexible Payment Options: EPP, Easy Loan and Balance Transfer
NBQ attaches three repayment tools to its cards. They are useful when used deliberately and costly when used by habit.
Easy Payment Plan (EPP) converts a large purchase into instalments with no processing fee. Monthly rates are 0.90% for 3 months, 0.80% for 6 months and 0.70% for 12 months. Cancelling an EPP early costs AED 210.
Easy Loan Scheme (ELS) turns available credit into a cash loan. Monthly rates run from 0.90% over 12 months down to 0.50% over 48 months, with a 1.05% processing fee. Early settlement costs 1.05% of the remaining balance.
Balance Transfer (BT) moves debt from another bank’s card. For shorter terms of 3, 6 and 12 months, NBQ charges a one-time processing fee of 1.0%, 1.5% and 2.0% respectively. Terms of 18 to 48 months carry a reducing rate of 0.50% per month. Early closure costs 1.05% of the outstanding amount.
A balance transfer makes sense only if you can finish repaying before the promotional structure ends and you stop adding new debt. Otherwise you are simply moving the problem.
Transaction Limits, Security and Digital Wallets
NBQ publishes daily limits by card tier.
| Transaction type | Gold and Platinum* | Infinite |
|---|---|---|
| ATM cash withdrawal | 3 per day, AED 5,000 | 3 per day, AED 5,000 |
| Online payments | 10 per day, AED 20,000 | 10 per day, AED 100,000 |
| Point of sale | 20 per day, up to AED 100,000 each | 20 per day, up to AED 200,000 each |
*The limits shown on the Gold page are listed here. Check the Platinum page before quoting them for that tier.
Contactless payments work without a PIN up to AED 500. NBQ cards can be added to Apple Pay and Samsung Wallet, and the bank’s mobile app lets you view limits and balances, pay card bills and block a lost card instantly. Card bills can also be paid through branches, cash deposit machines, online banking and UAE Exchange, Al Ansari Exchange and Al Fardan Exchange outlets.
For any suspected fraud, call NBQ on 600 56 56 56 immediately and block the card in the app first.
How to Apply for an NBQ Credit Card
- Check your tier. Match your salary to the Gold or Platinum band. If you earn AED 30,000 or more, ask about Infinite.
- Gather documents. Emirates ID, passport and proof of income.
- Apply online or in branch. Each card page on the NBQ website has its own application form, and the bank says it will contact you within 24 hours of a request.
- Wait for credit assessment. Approval is subject to the bank’s credit review, which includes your credit report from the Al Etihad Credit Bureau.
- Read the Key Facts Statement before signing. You have a five-business-day cooling-off period to withdraw unless you waived it in writing.
- Activate and set up the app. Add the card to your wallet and set up payment reminders.
If you are unsure about your standing, check your credit report first. Our guide to credit card score checks in the UAE explains how.
Who Should Choose Which NBQ Card?
Choose Gold if you want a card with no annual fee, you earn at least AED 8,000 and you value built-in travel insurance. The trade-off is no lounge access and a lower online limit.
Choose Platinum if you travel several times a year and will use the lounges. The trade-off is a AED 500 fee you pay whether you travel or not.
Choose Infinite if you are invited and want high limits, concierge support and waived service fees. The trade-off is a AED 1,000 fee, and the benefits only pay off with heavy use.
Across the whole range, the main advantages are transparent fees, no mandatory salary transfer and strong insurance cover. The main drawbacks are a relatively high salary floor, a 29.88% APR that makes carrying debt expensive, and a rewards structure that looks lighter than the points-heavy cards from larger banks.
Common Mistakes to Avoid
- Paying only the minimum. It keeps your account in good standing but makes the card very expensive.
- Using the card for cash. A 3.15% fee plus AED 21 and immediate interest make cash advances one of the costliest ways to borrow.
- Accepting dirham conversion abroad. The fee stacks on the merchant’s margin.
- Ignoring the due date. The AED 157.50 late fee can also damage your credit record, as NBQ itself warns.
- Treating the limit as spendable income. Banks also look at your debt burden, and a high balance can reduce your chances of a loan later.
- Buying a premium card you will not use. Annual fees are not refunded if you cancel.
Smart Habits for NBQ Cardholders
Set a direct debit for the full statement balance rather than the minimum. This keeps you inside the 55-day interest-free window every month and builds a clean payment history. Use the app to check your available limit before large purchases, and request a temporary limit increase only when you truly need one, since it costs AED 52.50.
If you want to cancel, remember that the full outstanding balance becomes due immediately and that annual fees are not refunded. Time your cancellation just before the annual fee posts, not just after.
Your Rights as an NBQ Cardholder
NBQ commits to give you 60 calendar days’ notice before changing terms and conditions. Complaints should receive a response within 10 working days through the call centre (600 56 56 56) or customercare@nbq.ae. If a complaint stays unresolved, you can take it further through the Central Bank of the UAE’s consumer protection channels.
Offers and Outlook
NBQ ran a new-cardholder cashback campaign that paid AED 250 on AED 5,000 of retail spend and AED 500 on AED 10,000 within 60 days of issuance. That campaign was valid until 30 April 2026, so confirm with the bank whether a replacement exists before promising it to readers.
Looking ahead, NBQ continues to invest in digital channels, with Apple Pay, Samsung Wallet and the Aani payment app now supported. Expect competition for mid-income customers to keep intensifying, so it is worth checking the bank’s schedule of fees each year.
FAQs
1. What is the minimum salary for an NBQ credit card?
The minimum monthly salary is AED 8,000, which qualifies you for the Gold card. Platinum starts at AED 15,000 and Infinite at AED 30,000.
2. Does NBQ offer a free credit card?
Yes. The Gold card has no annual subscription fee. Platinum costs AED 500 and Infinite AED 1,000.
3. Do I need to transfer my salary to NBQ?
No. According to NBQ’s Key Facts Statement, salary transfer is not mandatory. You still need to provide proof of income.
4. Can expatriates apply for an NBQ credit card?
Yes. UAE nationals and residents aged 21 or older can apply, provided they meet the salary and service requirements.
5. How many interest-free days do NBQ cards give?
Up to 55 days on retail purchases when you pay the full statement balance by the due date. Cash advances and balance transfers earn no interest-free period.
6. What is the NBQ credit card interest rate?
The APR is 29.88%, or 2.49% per month, on both purchases and cash advances.
7. Does the NBQ Platinum card include airport lounge access?
Yes, through Priority Pass. NBQ’s key facts document cites more than 1,200 lounges in 143 countries, while its website says more than 1,300.
8. Can I get a supplementary card?
Yes. NBQ gives one supplementary card free for a family member on its Gold, Platinum and Infinite cards.
9. How can I apply for the NBQ Infinite card?
Infinite is by invitation only. Speak with your NBQ relationship manager or branch about eligibility, particularly if you earn AED 30,000 or more.
10. Can self-employed people get an NBQ credit card?
Yes, but the criteria are stricter: three years in business, AED 500,000 annual turnover and a bank balance supporting twice the requested limit.
11. What happens if I miss a payment?
NBQ charges AED 157.50 per month, interest continues on the balance and the delay may affect your credit rating.
12. How do I report a lost NBQ card?
Block it immediately in the NBQ mobile app, then call 600 56 56 56 for a replacement. Replacement costs AED 78.75 on Gold and Platinum and is free on Infinite.
Conclusion
The NBQ credit card range rewards applicants who value clarity over gimmicks. Gold gives you a fee-free card with real travel insurance, Platinum adds lounge access for frequent flyers, and Infinite offers high limits and concierge service to invited clients. None of the cards require a salary transfer, and the fee schedule is published in plain terms.
The weak point is the same as with every UAE credit card: the 29.88% APR makes carried balances expensive. Pay in full each month, avoid cash advances, choose local currency abroad, and any of the three NBQ cards can be a low-cost, dependable tool. Match the tier to your income and travel habits, read the Key Facts Statement, and confirm current terms with the bank before you apply.
Sara is a UAE-based banking and accounting expert with over 4 years of professional experience in the financial sector. Her expertise spans retail banking, financial reporting, compliance, and practical money management topics relevant to individuals and businesses in the UAE.
She contributes clear, accurate, and well-researched financial content, simplifying complex banking and accounting concepts for everyday readers. Sara’s writing reflects strong industry knowledge, regulatory awareness, and a commitment to financial accuracy and transparency.