American Express Credit Card UAE Guide: Cards, Fees, Eligibility and How to Apply
An American Express credit card in the UAE is a rewards card issued by AMEX (Middle East) B.S.C. (c) – Emirates. The range includes the Gold Credit Card, Dubai Duty Free Card and Platinum Credit Card, plus the premium Platinum Card. You must be 21, a UAE resident with an Emirates ID, and meet each card’s minimum monthly income.
American Express credit card
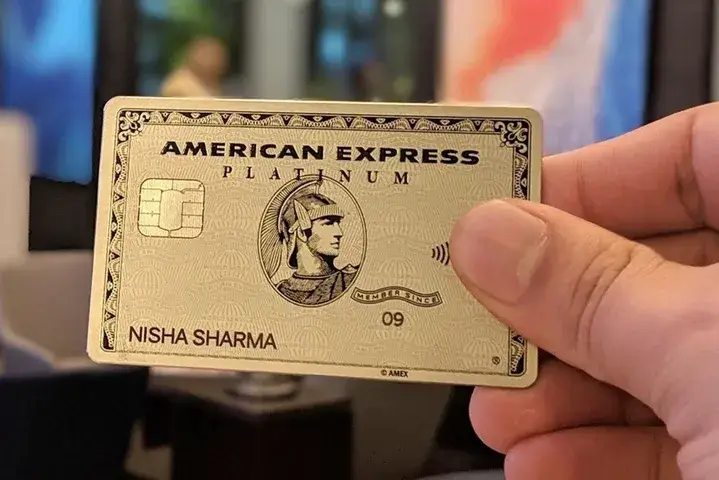
Ask ten people in Dubai which card they carry, and nine will name a Visa or a Mastercard. The tenth will probably reach for a card with a different logo and a different philosophy. An American Express credit card in the UAE is not built to be the most widely accepted piece of plastic in your wallet. It is built to reward people who spend steadily, travel often and care about perks more than convenience.
This guide explains how that works in practice. You will see which American Express cards are available to UAE residents, what each one costs, who qualifies, how the Membership Rewards programme turns everyday spending into points, and where the cards fall short. Whether you are comparing the entry-level Gold Credit Card with the Platinum Credit Card, or wondering if the top-tier Platinum Card is worth its fee, the sections below follow the same order a careful applicant would think through the decision.
A quick note on figures. Fees, income thresholds and welcome offers change with campaigns, so treat every number here as a snapshot and confirm it on the issuer’s UAE website before you apply.
What Is an American Express Credit Card in the UAE?
American Express is a global payments company and a card network. That makes it different from most banks you deal with in the Emirates. When you hold a Visa from Emirates NBD or a Mastercard from ADCB, the bank issues the card and a separate network moves the money. With American Express, the company usually plays both roles: it runs the network and it lends to you directly.
In the UAE, cards are issued by AMEX (Middle East) B.S.C. (c) – Emirates. According to the issuer’s own cardmember documents, this entity is the UAE branch of a financing company and is regulated and licensed by the Central Bank of the UAE. The parent financing company is licensed by the Central Bank of Bahrain. In plain terms, your application, your credit limit, your statements and your complaints all go to American Express, not to a high-street bank.
This structure explains a lot of what follows. Approval standards are set centrally. Rewards sit inside one programme, Membership Rewards. And merchant acceptance depends on whether a shop has signed up to the American Express network, which is a separate decision from accepting Visa or Mastercard.
The American Express Cards Available to UAE Residents
American Express offers a small range in the UAE rather than the dozens of variants a local bank might list. The table below puts the main cards side by side. Think of it as a map before we walk through each card in detail.
| Card | Type | Annual fee (incl. 5% VAT) | Minimum monthly income | Headline benefit |
|---|---|---|---|---|
| Dubai Duty Free American Express Card | Credit card | AED 183.75 | About AED 15,000 | 10% savings at Dubai Duty Free |
| American Express Gold Credit Card | Credit card | AED 414.75, plus AED 99.75 Membership Rewards fee | AED 15,000 | Entry route into Membership Rewards |
| American Express Platinum Credit Card | Credit card | AED 735 | AED 21,250 | 2 points per AED 4 spent, airport lounge visits |
| The Platinum Card | No pre-set spending limit | AED 3,255 | AED 31,500 | Annual travel credit, wide lounge access |
Source basis: issuer’s UAE product pages and schedule of fees and charges. Figures were checked in October 2026 and may have changed since.
American Express Gold Credit Card
The Gold Credit Card is the sensible starting point for most residents. It carries an annual membership fee of AED 395 (AED 414.75 with VAT), and you pay a separate Membership Rewards fee of AED 95 (AED 99.75 with VAT) once you enrol in the points programme. The minimum monthly income is AED 15,000.
You earn one Membership Rewards point for every AED 4 you spend on eligible purchases. Supplementary cards are free, up to nine of them, which matters for families who want to put household spending on one account.
The cardmember schedule also lists the charges you should know about before signing: a late payment fee of AED 230, an overlimit fee of AED 190, and a cash withdrawal limit of 40% of your credit limit. We will come back to these under common mistakes.
Dubai Duty Free American Express Card
This card is aimed at people who actually pass through Dubai’s airports, and it is the cheapest in the range. The annual fee is AED 175 (AED 183.75 with VAT), and supplementary cards are free, again up to nine. The headline benefit is a 10% saving on purchases at Dubai Duty Free, and the schedule of fees lists an interest-free period on purchases of up to 56 days.
If you buy perfume, electronics or gifts at the airport a few times a year, the maths can work quickly. If you rarely fly, the discount has little to bite on, and the Gold Credit Card will serve you better.
American Express Platinum Credit Card
Here the fee rises to AED 700 (AED 735 with VAT), and the minimum monthly income to AED 21,250. In exchange, you earn two Membership Rewards points for every AED 4 spent, double the Gold rate. Newly approved cardmembers have been offered 20,000 welcome points.
Two features soften the fee. First, a FeeBack arrangement credits the annual fee when you spend at least AED 10,000 in the first three months. Second, the card includes complimentary global airport lounge access through Priority Pass for up to 12 visits with a guest. The issuer also lists retail insurance of up to AED 5,400 and travel accident insurance of up to AED 1,800,000.
The Platinum Card
This is the flagship. The annual membership fee is AED 3,100 (AED 3,255 with VAT), and the published minimum monthly income is AED 31,500. It carries no pre-set spending limit, which means it works differently from a standard credit card. Your spending power adapts to your profile and payment record rather than sitting under a fixed ceiling, and balances are generally expected to be settled promptly. Read the cardmember agreement closely for the exact repayment terms.
Benefits include complimentary airport lounge access for you and a supplementary cardmember at over 1,300 lounges worldwide, an annual travel credit of AED 1,100, complimentary hotel loyalty programme enrolment, and access to “Platinum Experiences” across dining, wellness, shopping and entertainment. Recent campaigns have also offered 30,000 welcome points and a welcome credit for reaching a spending target.
This card suits a narrow audience: people who travel often enough to use the lounge and travel-credit perks, and who would spend heavily anyway.
American Express Credit Card Eligibility in the UAE
Eligibility is where most applications succeed or fail, so it deserves care. Across the range, the issuer asks you to meet a short list of conditions:
- Be at least 21 years old.
- Meet the minimum monthly income stated for the card you choose.
- Hold a valid Emirates ID.
- Hold a valid UAE IBAN and a UAE address.
Notice what is missing: a strict salary transfer requirement is not part of the published criteria, which is one reason some applicants prefer American Express over bank-issued cards. Income can be shown as a salaried employee or as a self-employed person, though self-employed applicants are normally assessed on annual income and must show business bank statements.
Documents You Will Typically Need
Expect to provide your Emirates ID, your passport with a valid residence visa, and recent bank statements showing income. Salaried applicants may also be asked for a salary certificate. Self-employed applicants usually provide a trade licence and company statements. Requirements shift, so the application portal is the final authority.
Credit Score, Debt Burden and Approval
Income alone does not guarantee approval. Like any lender in the Emirates, American Express looks at your credit history through the Al Etihad Credit Bureau (AECB). Missed instalments, defaults and heavy existing borrowing all count against you. A high balance on other cards can also push up your debt burden ratio, the share of monthly income already committed to repayments. Banks and finance companies commonly keep total obligations below roughly half of income, so check your own figures before applying.
If you are unsure where you stand, review your AECB report first. We cover that process in our guide to checking your credit score in the UAE.
How Membership Rewards Works
Membership Rewards is the heart of the American Express proposition. Every eligible purchase earns points, and the points are yours to spend on a range of rewards.
The earn rates are simple. The Gold Credit Card gives one point for every AED 4 spent. The Platinum Credit Card gives two points for every AED 4. Run the numbers on a household that spends AED 5,000 a month on the card: that is AED 60,000 a year, which earns about 15,000 points on Gold and about 30,000 on the Platinum Credit Card. The second card costs more to hold, but it doubles the rate, so heavier spenders recover the difference faster.
Points do not expire, according to the issuer, which removes the annual rush to redeem that many local loyalty schemes create. On the redemption side, the Platinum Credit Card page lists 14 airline partners, three hotel partners and merchandise from fashion and electronics brands.
One practical tip: compare what a point buys before you chase a redemption. Flight redemptions and merchandise redemptions give different value per point, and the better one depends on the route and the season. Always check the live redemption catalogue rather than assuming a fixed dirham value.
Do remember the Membership Rewards fee on the Gold Credit Card. It is a real cost that offsets part of your earning, so the card makes the most sense when your annual spending is comfortably above a few tens of thousands of dirhams.
Amex Offers and Everyday Perks
Beyond points, American Express runs Amex Offers, a rotating list of local and global promotions loaded to your card. These can include dining discounts, shopping credits and travel deals. They require activation and often have a spending cap, so they reward people who read the offer terms and plan a purchase around them.
The premium cards add insurance and service layers. Retail protection, travel accident cover and, on the Platinum Card, a dedicated 24/7 services line all sit under this heading. Treat the coverage amounts as headline figures: eligibility, exclusions and claim procedures live in the cardmember insurance documents.
Fees and Charges to Understand Before You Apply
A card’s headline fee tells only part of the cost story. Here is what else deserves attention.
Annual membership fee. The amounts are in the table above. VAT at 5% is added, so the fee on your statement is slightly higher than the base figure advertised in some campaigns.
Membership Rewards fee. On the Gold Credit Card this is a separate annual charge if you enrol.
Late payment and overlimit fees. On the Gold Credit Card the schedule lists AED 230 for late payment and AED 190 for exceeding your limit, each with VAT on top.
Cash advance charges. Withdrawing cash is expensive on almost every card. The Gold schedule shows a limit of 40% of your credit limit and a transaction charge that is the greater of a percentage or a fixed dirham amount. Interest starts immediately, with no interest-free period.
Interest on balances. Revolving a balance is the quickest way to wipe out any rewards you earn. Interest rates change, so read the current rate in your cardmember agreement rather than relying on a figure from an old brochure.
Foreign currency conversion. Spending abroad usually carries a conversion or processing margin. Confirm the current rate if you plan to use the card for overseas travel.
American Express vs Visa and Mastercard in the UAE
This comparison is where honest advice matters most. American Express wins on service and rewards. It loses on acceptance.
Acceptance. Large hotels, airlines, malls and international retailers in Dubai and Abu Dhabi generally accept American Express. Smaller shops, some restaurants and many taxi and delivery services may not, or may add a surcharge. If you want one card that works everywhere, Visa or Mastercard remains the safer pick.
Rewards. The Membership Rewards structure is straightforward, and points that do not expire are a genuine advantage over schemes with short validity windows.
Approval route. Because American Express is the lender, you are not tied to a banking relationship. A bank-issued card may be easier to get if you already bank with that institution and receive your salary there.
Support. Cardmembers consistently value direct access to the issuer, particularly on the premium cards.
The practical solution many residents choose is a two-card setup: American Express for the spending where it is accepted and rewarded, plus a Visa or Mastercard as a backup.
Who Should Choose Which Card?
Match the card to your behaviour, not your aspirations.
If your monthly income is near AED 15,000 and you want a first premium-brand card, start with the Gold Credit Card or, if you shop at Dubai’s airports, the Dubai Duty Free Card.
If you spend steadily, travel a few times a year and want lounge visits, the Platinum Credit Card is the natural step up, especially if you can hit the FeeBack spending target.
If you fly frequently, value lounges and travel credits, and already clear the income threshold with room to spare, The Platinum Card may repay its fee. If you cannot name the benefits you would actually use, it will not.
Step-by-Step: How to Apply for an American Express Credit Card in the UAE
- Check your credit report. Review your AECB report for errors and unsettled balances. Fixing a mistake before you apply is easier than appealing a refusal.
- Confirm your income against the card’s threshold. Use your monthly income, not your target income.
- Choose one card. Multiple applications in a short window leave a trail of enquiries that lenders notice.
- Gather documents. Emirates ID, passport, residence visa, recent bank statements, and a salary certificate or trade licence as relevant.
- Apply through the issuer. Use the official UAE website or the American Express MENA mobile app, or request a call-back from a representative.
- Respond quickly to follow-ups. Verification calls and document requests are common.
- Activate and enrol. Once approved, activate the card and decide on Membership Rewards enrolment.
Common Mistakes to Avoid
Applying above your income band. A declined application can affect how future applications are viewed. Choose a card you clearly qualify for.
Paying only the minimum. Interest on carried balances quickly outweighs any rewards. If you cannot clear the statement, use the card less.
Ignoring the fee break-even. Add up the annual fee, the Membership Rewards fee and your realistic yearly spending before you commit.
Using cash advances. The cost is high and immediate.
Leaving points idle. Even if points do not expire, they lose value if you never plan a redemption. Check the live catalogue a couple of times a year.
Forgetting acceptance gaps. Carry a backup card, particularly when you travel or eat out away from major venues.
Expert Insight: Is an American Express Credit Card Worth It?
The honest answer depends on your spending pattern. For a resident who spends AED 4,000 to 6,000 monthly on groceries, utilities, dining and travel, and who can use the card at most of those merchants, the earn rates and perks are competitive. For a resident who mainly pays in places that only accept Visa or Mastercard, the card becomes a decoration with an annual fee.
A useful test: list your five biggest monthly spending categories and check whether each accepts American Express. If at least four do, the card can carry real weight in your wallet.
Future Outlook
Several trends will shape how American Express cards evolve in the UAE. Digital applications through mobile apps are making onboarding faster. Contactless and wallet payments are expanding merchant acceptance, since many terminals now handle multiple networks. And UAE regulation continues to emphasise transparent fees and responsible lending, which favours issuers that disclose charges plainly. Expect welcome offers and fee structures to keep changing, which is another reason to verify details on the day you apply.
FAQs
1. What is the minimum salary for an American Express credit card in the UAE?
It depends on the card. The published minimum monthly income is AED 15,000 for the Gold Credit Card, AED 21,250 for the Platinum Credit Card and AED 31,500 for The Platinum Card.
2. What is the minimum age to apply?
You must be at least 21 years old.
3. Which American Express card is best for beginners?
The Gold Credit Card is the usual entry point for premium-brand rewards, while the Dubai Duty Free Card has the lowest annual fee for frequent airport shoppers.
4. Do American Express points expire?
According to the issuer, Membership Rewards points do not expire. Always confirm programme terms in your account.
5. How much is the annual fee of the Platinum Credit Card?
AED 700, or AED 735 including 5% VAT. Offers have allowed the fee to be credited back after spending AED 10,000 in the first three months.
6. Can I get an American Express card without a salary transfer?
The published eligibility criteria focus on age, income, residency, Emirates ID and a UAE IBAN rather than a salary transfer. Confirm during application.
7. Can self-employed people apply?
Yes. Self-employed applicants are generally assessed on annual income and asked for business bank statements.
8. Is American Express accepted everywhere in the UAE?
No. Major hotels, airlines and malls generally accept it, but smaller merchants may not. Carrying a Visa or Mastercard as backup is wise.
9. Does American Express offer airport lounge access?
The Platinum Credit Card lists Priority Pass lounge visits (up to 12 with a guest), and The Platinum Card includes lounge access for the cardmember and a supplementary cardmember.
10. How do I apply?
Apply through the issuer’s official UAE website or the American Express MENA mobile app, or request a call-back from a representative.
11. What documents are required?
Typically your Emirates ID, passport, and recent bank statements, plus a salary certificate for employees or a trade licence for self-employed applicants.
12. Is The Platinum Card a credit card?
It has no pre-set spending limit, so it works differently from a standard credit card. Review the cardmember agreement for repayment terms.
Conclusion
An American Express credit card in the UAE is a specialist tool rather than an all-purpose card. The Gold Credit Card and the Dubai Duty Free Card give residents with a mid-level income an affordable way into the Membership Rewards programme. The Platinum Credit Card raises the earn rate and adds lounge access for a moderate fee. And The Platinum Card serves frequent travellers who will truly use its credits and lounges.
The decision comes down to three checks. Do you meet the income threshold comfortably? Will your annual spending outweigh the fees? And do your regular merchants accept American Express? If the answer to all three is yes, apply with a clear conscience. If not, a Visa or Mastercard may serve you better, and an American Express card can wait until your spending pattern fits it.
Sara is a UAE-based banking and accounting expert with over 4 years of professional experience in the financial sector. Her expertise spans retail banking, financial reporting, compliance, and practical money management topics relevant to individuals and businesses in the UAE.
She contributes clear, accurate, and well-researched financial content, simplifying complex banking and accounting concepts for everyday readers. Sara’s writing reflects strong industry knowledge, regulatory awareness, and a commitment to financial accuracy and transparency.