Mashreq Cashback Credit Card in UAE: Complete 2027 Guide
Choosing a credit card in the UAE involves more than comparing cashback percentages. Annual fees, spending categories, interest rates, and redemption rules all determine whether a card genuinely saves you money.
The Mashreq Cashback Credit Card is a popular option for UAE residents who regularly spend on restaurants, food delivery, shopping, and other everyday purchases. With dining cashback of up to 5%, no annual fee, and a welcome bonus for eligible applicants, it offers a straightforward rewards programme.
However, not every purchase earns the advertised 5%, and certain transactions receive significantly lower rewards.
This guide explains how the card works, its benefits, eligibility requirements, fees, cashback calculations, application process, and limitations to help you decide whether it suits your spending habits.
What Is the Mashreq Cashback Credit Card?
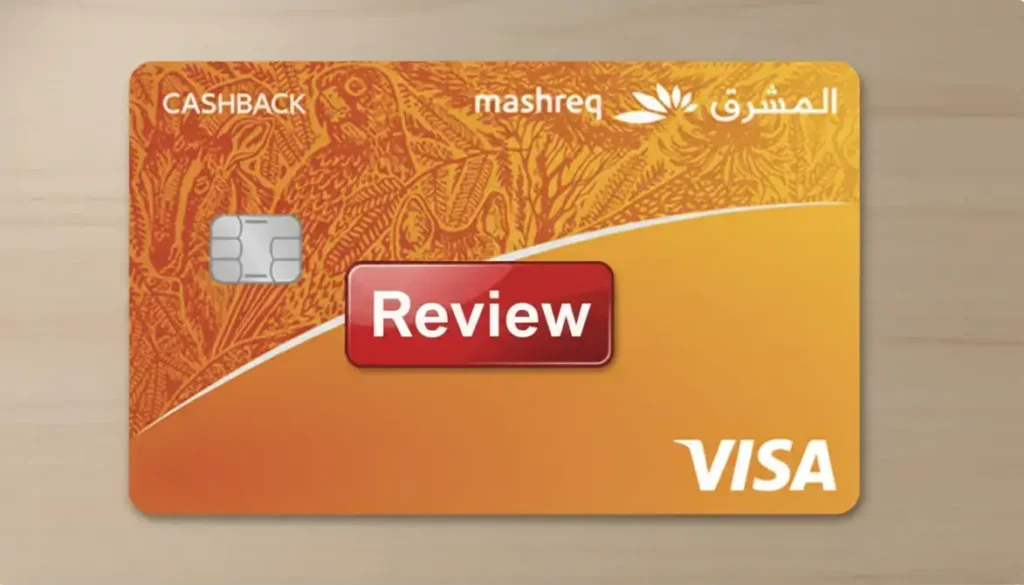
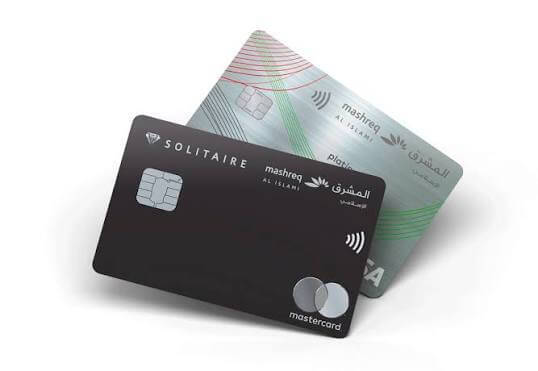
The Mashreq Cashback Credit Card is a Visa credit card issued by Mashreqbank in the United Arab Emirates. It offers 5% cashback on eligible local and international dining, 1% on most other purchases, and 0.15% on selected categories such as fuel, utilities, and government payments. It has no annual fee and requires a minimum monthly salary of AED 5,000.
Unlike traditional reward-point programmes, cashback provides a monetary benefit based on eligible card spending. The amount earned can be redeemed as a credit against the card’s outstanding balance once the redemption threshold is reached.
Mashreqbank is a UAE-based financial institution regulated by the Central Bank of the United Arab Emirates (CBUAE).
Mashreq Cashback Credit Card Features at a Glance
Before examining the benefits, here is an overview of the card’s main features and conditions.
| Feature | Details |
|---|---|
| Card provider | Mashreqbank |
| Card network | Visa |
| Minimum monthly salary | AED 5,000 |
| Annual fee | Free for life |
| Dining cashback | 5% |
| Other international purchases | 1% |
| Other eligible UAE purchases | Up to 1% |
| Fuel, utilities, education and selected categories | 0.15% |
| Minimum cashback redemption | AED 100 |
| Interest-free period | Up to 57 days |
| Retail interest rate | 46.20% per annum |
| Minimum monthly payment | 5% of statement balance |
| Supplementary card annual fee | Free for life |
| Standard cashback validity | Up to 36 months |
These details reflect the card’s published conditions as reviewed in November 2026. Promotional benefits, fees, and eligibility requirements may change.
How Does the Mashreq Cashback Credit Card Work?
The card rewards eligible purchases by calculating cashback according to the transaction’s spending category.
For example, spending at an eligible restaurant generally earns a higher reward than paying a utility bill or purchasing fuel.
The calculation follows a simple formula:
Cashback earned = Eligible transaction amount × Applicable cashback percentage
Suppose you spend AED 500 at a qualifying restaurant.
AED 500 × 5% = AED 25 cashback.
If you spend the same AED 500 at an ordinary retail store qualifying for 1%, the reward becomes AED 5.
The difference illustrates why understanding the spending categories matters more than focusing only on the maximum advertised rate.
Cashback generally becomes visible in Mashreq’s mobile banking service within two to three working days after an eligible transaction is posted.
The bank’s terms also allow monthly cashback totals to be rounded down to the nearest dirham.
What Counts as an Eligible Transaction?
Mashreq uses merchant category codes (MCCs) to identify the type of business processing a payment.
These codes help distinguish restaurants, fuel stations, educational institutions, government services, and other merchants.
For this reason, two purchases that appear similar to a customer may earn different cashback rates if the merchants are classified differently.
A food purchase made through a merchant registered under an eligible dining category may qualify for 5%, while a grocery transaction generally falls under another spending category.
Mashreq Cashback Credit Card Benefits
The card’s advantages extend beyond the headline dining cashback. Several features can make it useful for everyday spending, particularly when balances are repaid in full.
1. Earn 5% Cashback on Dining in the UAE and Abroad
Dining is the card’s strongest everyday rewards category.
Eligible spending at restaurants, cafés, and qualifying food delivery merchants can earn 5% cashback.
For example:
- AED 200 spent on dining earns AED 10.
- AED 800 spent on dining earns AED 40.
- AED 2,000 spent on dining earns AED 100.
The card can be particularly attractive to residents of Dubai, Abu Dhabi, Sharjah, and other emirates who frequently order food or visit restaurants.
Mashreq does not advertise a separate monthly dining cashback cap in its standard published card benefits. However, cashback is subject to qualifying merchant categories and the card’s assigned credit-limit rules.
International dining may attract foreign transaction charges, so the net benefit can be lower than the advertised reward.
2. Earn 1% Cashback on Other Eligible Purchases
For purchases outside the dining category, the Mashreq Cashback Credit Card generally offers 1% cashback on eligible international spending and up to 1% on other local retail purchases.
Examples may include:
- Supermarket shopping
- Clothing and accessories
- Electronics
- Household products
- Eligible online retail purchases
A qualifying AED 3,000 retail purchase at a 1% rate would generate AED 30 cashback.
However, categories such as fuel, education, rent, utilities, and government payments have separate, lower rates.
3. No Annual Fee for Life
One of the card’s main advantages is its lifetime annual-fee waiver.
Both primary and supplementary cards have no annual membership fee.
This is helpful for people who want cashback benefits without paying a recurring membership charge.
Nevertheless, no annual fee does not mean the card is completely free to use.
Interest, international transaction charges, late payment fees, and other applicable costs can still arise.
4. Welcome Bonus for Eligible Customers
Mashreq advertises a welcome cashback offer for qualifying applicants.
Under the published promotion:
| Customer category | Welcome bonus | Spending requirement |
|---|---|---|
| New Mashreq credit card customers | AED 500 | AED 5,000 within the first two months |
| Eligible existing credit card customers | AED 100 | AED 5,000 within the first two months |
The welcome bonus is separate from ordinary cashback.
For example, a qualifying new customer who spends AED 5,000 during the promotional period may receive the AED 500 welcome reward, alongside any standard cashback earned on eligible transactions.
Promotional eligibility depends on the bank’s customer definitions and applicable conditions. The advertised offer should be checked when applying, as the bank may change or withdraw it.
Importantly, customers should not make unnecessary purchases merely to meet a promotional spending target.
5. Selected Merchant Cashback Offers
Mashreq also advertises promotional cashback at selected digital and lifestyle merchants.
These have included brands such as Careem, Talabat, Netflix, and other participating services.
One advertised promotion provides 20% cashback during the first four months, subject to a maximum of AED 50 per merchant each month.
Such offers are different from the card’s standard rewards programme.
Customers should confirm merchant participation, promotional validity, transaction requirements, and cashback limits before relying on these additional benefits.
6. Dining, Entertainment and Travel Offers
Eligible cardholders may also access selected Visa and Mashreq partner promotions.
Depending on the offer, these may include restaurant discounts, entertainment savings, cinema promotions, and travel-related benefits.
These offers can add value when they match purchases you already intend to make.
However, partner benefits should be treated as supplementary advantages rather than guaranteed long-term savings.
Mashreq Cashback Credit Card Cashback Rates Explained
Understanding the card’s category structure is essential because the highest cashback percentage applies only to particular transactions.
| Spending category | Standard cashback rate |
|---|---|
| Eligible local dining | 5% |
| Eligible international dining | 5% |
| Other international purchases | 1% |
| Other eligible UAE retail purchases | Up to 1% |
| Fuel | 0.15% |
| Utility payments | 0.15% |
| Government payments | 0.15% |
| Education | 0.15% |
| Telecommunications | 0.15% |
| Rent | 0.15% |
| Eligible charity payments | 0.15% |
The 0.15% rate is an important consideration for UAE households with significant monthly bills.
A customer spending AED 2,000 on eligible fuel and utilities would earn only AED 3 at that rate.
Furthermore, utility payments made through Mashreq’s own banking payment channels are excluded from cashback.
Why the 2026 Cashback Rate Matters
In 2026, the applicable cashback rate for selected categories became 0.15%, making it important to distinguish current benefits from older promotional information.
Customers comparing cards using outdated descriptions may overestimate the returns available on fuel, utilities, government transactions, and education payments.
The practical lesson is straightforward: calculate rewards separately for every major spending category rather than applying one cashback percentage to your entire monthly budget.
How Much Cashback Can You Earn Every Month?
To understand the card’s potential value, consider a hypothetical UAE resident with the following monthly expenses.
| Monthly expense | Amount | Rate | Estimated cashback |
|---|---|---|---|
| Restaurants and food delivery | AED 1,200 | 5% | AED 60 |
| Groceries | AED 1,500 | 1% | AED 15 |
| Shopping | AED 1,000 | 1% | AED 10 |
| Fuel | AED 600 | 0.15% | AED 0.90 |
| Utilities | AED 500 | 0.15% | AED 0.75 |
| Total | AED 4,800 | AED 86.65 |
In this illustrative scenario, the card generates approximately AED 86 in monthly cashback before considering the bank’s rounding rules.
If spending patterns remained unchanged for a full year, the theoretical annual cashback would be approximately AED 1,040.
Actual earnings depend on merchant classifications, excluded transactions, spending limits, account status, and other applicable terms.
The example also reveals something important: dining represents only one-quarter of total spending but contributes most of the estimated cashback.
This makes the card more suitable for customers with regular dining expenditure than for those whose budgets are dominated by bills and fuel.
Mashreq Cashback Credit Card Eligibility Criteria
Applicants must meet the bank’s eligibility and credit assessment requirements.
Minimum Salary Requirement
The published minimum monthly income is AED 5,000.
Meeting this threshold does not automatically guarantee approval.
Mashreq may also assess the applicant’s income stability, employment details, existing debt obligations, repayment history, and overall creditworthiness.
Age and Residency Requirements
Applicants must satisfy the bank’s applicable age and residency conditions.
As a general rule, conventional UAE credit card applications are intended for eligible adults, often from 21 years of age, subject to the issuer’s requirements.
UAE residents should verify the current age conditions directly with Mashreq rather than assuming that meeting the salary requirement is sufficient.
Credit History and Financial Profile
Banks evaluate repayment capacity before issuing credit.
In the UAE, credit information may be assessed through the Al Etihad Credit Bureau (AECB).
A credit report may include information about existing borrowing, outstanding obligations, and repayment behaviour.
Late payments, high existing debt, or insufficient documented income can affect an application.
The final credit limit and approval decision remain with the bank.
Documents Required for a Mashreq Cashback Credit Card
Applicants should prepare the identification and income documents requested during the application.
Depending on their employment and residency status, these may include:
- Valid Emirates ID
- Passport and UAE residence details
- Salary certificate or recent payslips
- Recent bank statements
- Employment information and contact details
Self-employed applicants may be asked for additional financial or business records.
The exact documentation can vary according to Mashreq’s verification procedures and the applicant’s financial profile.
How to Apply for a Mashreq Cashback Credit Card in the UAE
The application process can generally be completed through Mashreq’s official digital banking channels.
Step 1: Check Your Eligibility
Confirm that you meet the minimum income, age, residency, and other eligibility requirements.
Review your financial commitments and consider whether you can repay the card balance in full each month.
Step 2: Review the Card’s Current Conditions
Examine the benefits, promotional offers, interest rates, fees, and key facts statement.
Pay particular attention to the difference between cashback eligibility and welcome-bonus eligibility.
Step 3: Complete the Application
Visit Mashreq’s official credit card application service and select the Cashback Credit Card.
Enter the requested personal, employment, and income information accurately.
Step 4: Submit Supporting Documents
Provide the identification and income documents requested by the bank.
Additional checks may be required to verify the information.
Step 5: Await the Credit Decision
Mashreq will assess the application and determine whether to approve it.
Approval timing and credit limits depend on the individual case.
Step 6: Activate and Manage Your Card
Once the card is issued, follow Mashreq’s activation instructions.
Eligible customers may receive digital card access, allowing supported transactions before physical delivery.
After activation, review transaction notifications, payment dates, spending limits, and cashback information through the bank’s digital services.
Mashreq Cashback Credit Card Fees and Charges
Although the card has no annual fee, other charges can significantly affect its value.
| Fee or charge | Published amount |
|---|---|
| Primary annual fee | AED 0 |
| Supplementary annual fee | AED 0 |
| Retail interest | 46.20% annually |
| Foreign-currency transaction spread | 2.89%, plus applicable network charges |
| Late payment fee | AED 241.50 |
| Cash advance fee | 3.15% or AED 210, whichever is higher |
| Over-limit fee | AED 303.45 |
| Card replacement fee | AED 78.80 |
The fee amounts shown reflect the reviewed Mashreq key facts documentation. Charges may be revised, and customers should check the latest schedule before making a financial decision.
Understanding Interest Charges
The card’s published annual retail interest rate of 46.20% is equivalent to a nominal monthly rate of 3.85%.
This makes outstanding credit card debt potentially expensive.
For example, a customer carrying an unpaid balance of AED 5,000 could face substantial finance charges over time, depending on the transaction dates, repayments, and applicable interest-calculation rules.
Those charges can quickly exceed ordinary cashback earnings.
The most effective way to protect cashback savings is to pay the entire statement balance by the due date, subject to the card’s applicable interest-free conditions.
Foreign Transaction Charges
International purchases deserve additional attention.
Although eligible foreign-currency transactions may earn 1% cashback, the card also has a published 2.89% foreign transaction spread, with additional network charges potentially applicable.
A hypothetical AED 1,000-equivalent international retail purchase earning AED 10 cashback could incur an AED 28.90 spread before any additional network charges.
The foreign transaction cost would therefore exceed the cashback reward.
International dining may earn a higher 5% rate, but customers should still compare the reward with the total conversion costs.
How to Redeem Mashreq Cashback
Cashback redemption is managed through Mashreq’s digital banking services.
The published minimum redemption amount is AED 100.
Cashback Redemption Process
- Sign in to Mashreq Mobile or online banking.
- Find the cashback balance or redemption section.
- Check the available eligible cashback.
- Select the redemption option and enter the permitted amount.
- Review and confirm the redemption.
Redeemed cashback is applied as a credit against the primary card account.
It is not normally transferred to a personal savings account as a cash withdrawal.
Does Cashback Reduce the Minimum Monthly Payment?
Cashback redemption can reduce the overall amount outstanding, but it does not count as the cardholder’s required minimum monthly payment.
For instance, if your statement shows a minimum payment due, redeeming cashback does not remove the obligation to make that payment.
Confusing cashback credits with actual repayments can lead to overdue payments and additional charges.
Does Mashreq Cashback Expire?
Yes. Standard earned cashback has a maximum validity of 36 months.
Accumulated rewards may also be forfeited in circumstances such as prolonged reward-account inactivity, account delinquency, or card closure under the applicable programme rules.
Regularly checking and redeeming eligible cashback helps avoid losing accumulated rewards.
Transactions That Do Not Earn Cashback
Not every credit card transaction qualifies for rewards.
Mashreq excludes several transaction types, including balance transfers, cash advances, credit card cheques, interest charges, bank fees, and reversed merchant transactions.
Utility bills paid through Mashreq’s own payment channels are also excluded.
Other transactions may become ineligible under the bank’s published conditions.
A useful distinction is that a transaction can be successfully processed using the credit card without necessarily earning cashback.
Before making a significant purchase specifically for a reward, confirm whether the merchant and transaction are eligible.
Mashreq Cashback Credit Card vs Mashreq noon Credit Card
Mashreq offers different reward structures for different spending habits.
Two cards that deserve comparison are its standard Cashback Credit Card and the Mashreq noon Credit Card.
| Feature | Mashreq Cashback Card | Mashreq noon Card |
|---|---|---|
| Main rewards focus | Dining and general spending | Participating noon-related purchases |
| Highlight reward | 5% on eligible dining | 5% on eligible partner purchases |
| Annual fee | Free for life | Free for life |
| Reward format | Cashback credited to card account | Platform-specific reward credits |
| Main advantage | Flexibility for restaurant spending | Potential savings within the partner ecosystem |
| Main limitation | Reduced rewards on selected everyday categories | Rewards are linked to qualifying partner platforms |
The better choice depends on where a customer regularly spends money.
Someone who frequently orders from eligible restaurants may favour the standard cashback product.
A person who makes substantial purchases through participating noon platforms may find the partner-focused alternative more relevant.
When comparing them, consider reward restrictions, redemption options, caps, and the actual cash value of benefits.
Mashreq Cashback Credit Card Advantages and Disadvantages
The card offers attractive features, but it is not equally suitable for every UAE consumer.
| Advantages | Disadvantages |
|---|---|
| No annual fee for primary and supplementary cards | High interest charges on unpaid balances |
| 5% cashback on eligible dining | Only 0.15% on several essential spending categories |
| No minimum spending requirement to start earning standard cashback | AED 100 minimum cashback redemption |
| Welcome bonus for eligible applicants | Foreign transaction charges can offset rewards |
| Cashback redemption through digital banking | Merchant classifications affect cashback |
| Potential lifestyle promotions | Cashback can expire or be forfeited |
The most important strength is the combination of dining cashback and no annual membership fee.
The main drawback is that the card’s rewards are less attractive when spending is concentrated in categories such as fuel, utilities, education, and rent.
Who Should Consider the Mashreq Cashback Credit Card?
The card may be suitable for UAE residents who regularly dine out, order food, and make eligible retail purchases.
It can also appeal to customers who want a cashback card without recurring annual fees.
However, the card’s potential value depends heavily on repayment habits.
A customer who pays the full statement balance each month is better positioned to benefit from the rewards than someone who regularly carries unpaid debt.
Who May Find Another Card More Suitable?
A different card may deserve consideration if:
- Most monthly spending goes towards fuel and utility bills.
- You frequently make international purchases where conversion fees matter.
- You prefer travel miles or airport-related benefits over cashback.
- You cannot consistently repay credit card balances in full.
Rather than selecting a card based on advertising alone, compare realistic annual rewards after fees and financing costs.
Practical Tips to Maximise Mashreq Cashback
The smartest cashback strategy is not to increase spending. It is to earn rewards on purchases that already fit your budget.
Prioritise Eligible Dining Purchases
Use the card for qualifying dining transactions where the 5% reward provides its strongest benefit.
Check the merchant category if a transaction unexpectedly receives a lower rate.
Pay the Full Statement Balance
Avoid carrying a balance merely to preserve cash for other purchases.
Finance charges can eliminate the financial advantage of cashback.
Monitor Your Cashback Balance
Review cashback accruals through Mashreq’s banking services and redeem accumulated rewards once eligible.
This helps identify missing rewards and reduces the risk of expiry.
Keep Foreign Currency Costs in Mind
When using the card internationally, compare cashback against transaction spreads and other conversion charges.
A rewards percentage should never be evaluated without considering the associated costs.
Review Promotional Conditions
Welcome bonuses and merchant promotions may be subject to time limits and separate eligibility rules.
Do not assume that benefits advertised during one promotional period will remain unchanged.
Common Mistakes to Avoid
Several misconceptions can make a cashback credit card less rewarding than expected.
Assuming every transaction earns 5%. The highest standard rate is mainly for eligible dining purchases.
Confusing minimum spending with minimum redemption. There is no minimum purchase amount required to start earning standard cashback, but redemption requires an accumulated balance of at least AED 100.
Ignoring payment dates. Missing the due date can result in fees, interest, and potential damage to creditworthiness.
Treating cashback as a bill payment. Redeemed rewards do not replace the required minimum monthly repayment.
Overlooking merchant classifications. Cashback depends partly on how the merchant processes and categorises the payment.
Spending unnecessarily to qualify for a bonus. Promotional rewards are rarely worthwhile if they encourage purchases that would not otherwise be made.
Avoiding these mistakes helps preserve the card’s intended financial benefits.
Is the Mashreq Cashback Credit Card Worth It in 2026?
For eligible UAE residents who spend regularly on dining and pay their credit card balances in full, the Mashreq Cashback Credit Card can provide meaningful savings without an annual membership fee.
Its 5% eligible dining cashback is the most compelling benefit.
However, the card is less impressive for households whose spending is dominated by utilities, petrol, education, and other reduced-rate categories.
The foreign transaction spread also makes it important to calculate the true benefit of overseas purchases.
Ultimately, the card’s value depends on three factors: your actual spending categories, the cashback you can realistically redeem, and the fees or interest you may incur.
A card that rewards your existing spending habits without encouraging extra borrowing is generally more useful than one offering a higher headline reward that rarely applies.
FAQs
1. What is the minimum salary for the Mashreq Cashback Credit Card?
The published minimum monthly salary requirement is AED 5,000. Approval also depends on the applicant meeting Mashreq’s additional eligibility, documentation, and credit assessment criteria.
2. Is the Mashreq Cashback Credit Card free for life?
Yes. Mashreq advertises no annual fee for both primary and supplementary cashback credit cards. Other charges, including interest, late payment fees, and foreign transaction costs, can still apply.
3. How much cashback does the Mashreq credit card offer?
The card offers 5% on eligible dining, 1% on other international purchases, up to 1% on other eligible local spending, and 0.15% on selected categories such as fuel, education, utilities, and government payments.
4. How can I apply for the Mashreq Cashback Credit Card online?
Visit Mashreq’s official credit card application service, review the eligibility requirements, complete the application, and provide any requested identity and income documentation. Approval is subject to the bank’s assessment.
5. What is the Mashreq Cashback Credit Card welcome bonus?
The advertised promotion offers AED 500 to qualifying new credit card customers and AED 100 to eligible existing customers, subject to spending at least AED 5,000 within the first two months. Terms and availability may change.
6. How do I redeem my Mashreq credit card cashback?
Eligible cashback can be redeemed using Mashreq’s online or mobile banking services. A minimum cashback balance of AED 100 is required, and redemption is credited to the primary credit card account.
7. Does Mashreq cashback expire?
Yes. Earned cashback generally remains valid for up to 36 months. Rewards can also be forfeited under certain inactivity, account status, or card closure conditions.
8. Does the Mashreq Cashback Credit Card offer cashback on fuel?
Yes. Eligible local fuel transactions earn 0.15% cashback under the current published rewards structure, subject to merchant classification and programme conditions.
9. Can I earn cashback on utility bills?
Eligible utility transactions can earn 0.15%. However, bill payments made through Mashreq’s own banking channels are excluded from cashback.
10. Is there a minimum spending requirement to earn cashback?
No. The standard rewards programme does not require a minimum purchase amount to begin earning cashback. Separate spending conditions apply to promotional welcome bonuses.
11. Can I use the Mashreq Cashback Credit Card internationally?
Yes. The Visa card can be used at eligible international merchants. However, foreign transaction spreads and applicable network charges can reduce or exceed the value of cashback earned.
12. Is the Mashreq Cashback Credit Card better than other UAE cashback cards?
It depends on spending habits. The card is particularly attractive for eligible dining transactions and its lack of annual fees. Consumers with larger fuel, grocery, utility, or travel budgets should compare category rates, spending conditions, caps, and overall costs before choosing.
Conclusion
The Mashreq Cashback Credit Card in the UAE offers a practical rewards structure for customers who regularly spend on dining and general retail purchases.
Its main advantages include 5% cashback on eligible dining, no annual fee, supplementary card benefits, digital redemption, and promotional rewards for qualifying customers.
Nevertheless, lower cashback rates on essential bills, international transaction costs, and potentially substantial interest charges should not be overlooked.
For UAE residents considering the card in 2026, the most sensible approach is to review the latest terms, calculate rewards using actual monthly spending, and ensure credit card balances can be repaid responsibly.
When used within a planned budget and repaid on time, the Mashreq Cashback Credit Card can be a useful tool for earning value from everyday purchases.
Sara is a UAE-based banking and accounting expert with over 4 years of professional experience in the financial sector. Her expertise spans retail banking, financial reporting, compliance, and practical money management topics relevant to individuals and businesses in the UAE.
She contributes clear, accurate, and well-researched financial content, simplifying complex banking and accounting concepts for everyday readers. Sara’s writing reflects strong industry knowledge, regulatory awareness, and a commitment to financial accuracy and transparency.